All Categories
Featured
Professional Staff Assistance EAP Resource Guidance
Table of Contents
If a group life ins plan fails these tests, crucial workers might lose the tax exemption, making their whole coverage quantity taxable. Charges for non compliance can be considerable. If a business's group life ins plan only covers executives or provides them better rates, the Internal revenue service might reclassify the advantage, resulting in extra taxes owed.
Some states even need continuation of group life ins coverage after work ends, beyond what federal COBRA laws provide. Companies should examine their group life ins policies for compliance with state regulations.
Keeping up with these mandates avoids legal conflicts and guarantees benefit continuity for staff. Managing delicate data is a core obligation when handling group life ins. Employers need to securely save recipient information, registration kinds, and claims paperwork. Compliance with HIPAA and similar privacy laws is vital to safeguard worker data.
Comprehensive Commercial Insurance and Employee Benefit Advice
Proper documentation supports regulatory compliance and staff member trust in the group life ins program. A thoughtful technique guarantees you optimize worth, support staff member well-being, and maintain compliance as you develop a competitive benefits plan.
Use confidential studies or focus groups to find what they value most in group life ins, such as portability, extra coverage, or dependent choices. Evaluation your budget and benchmark against industry norms. Think about both the expense of base protection and any additional functions, stabilizing monetary constraints with competitive offerings. For example, if a study exposes strong interest in buy-up choices, assign funds appropriately.
Selecting a provider for group life ins involves more than just comparing premiums. Evaluate insurance companies based on monetary stability, declares processing speed, and customer care credibility. Try to find carriers offering plan functions that match your workforce, such as sped up death advantages, waiver of premium, or unintentional death and dismemberment riders.
Future-Proofing Small Business Health Insurance for 2026
Choose whether your group life ins prepare will be employer-paid, voluntary, or a hybrid. Employer-paid protection frequently increases participation, while voluntary coverage permits employees to purchase extra defense for themselves or household.
Reliable education leads to notified choices and higher enrollment rates, guaranteeing that your group life ins prepare is both valued and made use of by your group. Efficient administration is key to a smooth group life ins experience.
A structured claims process, with clear paperwork requirements and timely assistance, builds trust among workers. Regularly evaluation administrative procedures to stay compliant and responsive, keeping your group life ins prepare running at peak efficiency. Screen participation rates, staff member feedback, and declares information to evaluate the efficiency of your group life ins plan.
Securing Small Business Health Insurance for 2026
Change protection amounts, include new features, or refine communication based upon what you learn. If workers request higher caps, consider increasing limitations in your next renewal cycle. Constant enhancement ensures your group life ins prepare develops with your workforce, keeping its value and significance year after year. Understanding the strengths and weak points of group life ins is essential for employers aiming to offer a well-rounded benefits package.
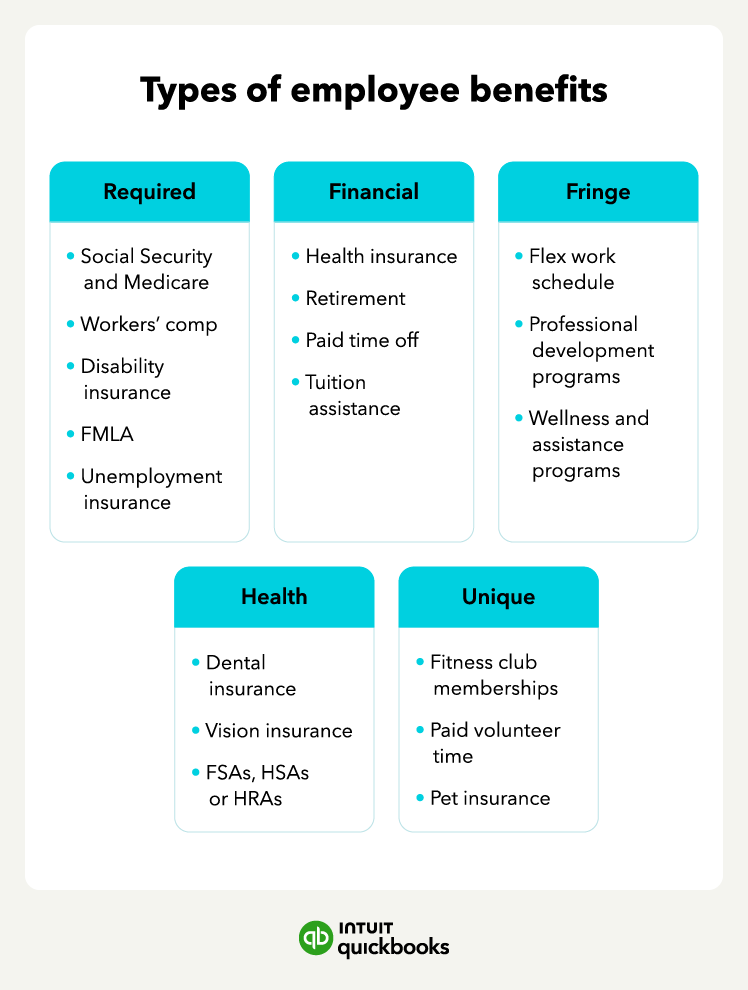
Group life ins supplies immediate monetary defense for staff members' families, providing comfort in the event of an unexpected loss. Employers can provide this benefit at little or no charge to personnel, making it an extremely valued addition to any compensation bundle. The uncomplicated qualification process, with very little medical underwriting, ensures most workers can register without complications.
Numerous organizations report enhanced recruitment and retention after adding group life ins. Beyond the basic death advantage, group life ins plans often include important optional functions.
Top Dental Insurance for Staff
Motivate staff members to complete beneficiary types and review protection options throughout open enrollment. Effective education causes notified decisions and higher enrollment rates, guaranteeing that your group life ins plan is both valued and made use of by your group. Effective administration is key to a smooth group life ins experience. Assign clear roles to HR or benefits groups for handling enrollment, payroll reductions, and claims support.
A structured claims process, with clear documentation requirements and timely support, builds trust among staff members. Regularly review administrative procedures to remain compliant and responsive, keeping your group life ins prepare operating at peak efficiency. Screen participation rates, worker feedback, and declares information to determine the effectiveness of your group life ins plan.
Constant improvement guarantees your group life ins plan evolves with your workforce, preserving its worth and significance year after year. Comprehending the strengths and weak points of group life ins is vital for companies intending to provide a well-rounded benefits package.
Integrating Payroll Insurance Options for Modern Teams
Group life ins provides immediate monetary defense for employees' families, providing peace of mind in case of an unexpected loss. Companies can provide this advantage at little or no charge to staff, making it an extremely valued addition to any settlement plan. The uncomplicated qualification procedure, with minimal medical underwriting, guarantees most employees can register without problems.
Lots of organizations report enhanced recruitment and retention after including group life ins. Beyond the fundamental death benefit, group life ins strategies typically include valuable optional functions.

Latest Posts

Comprehensive Commercial Insurance and Group Benefit Strategy

Expert Strategy for Small Enterprise Health Benefits

Securing the Business and Group Benefit Solutions